- calendar_today August 13, 2025
USD1 Stablecoin: Canada’s Digital Dollar Dilemma
“Bank of Canada faces stablecoin sovereignty test”
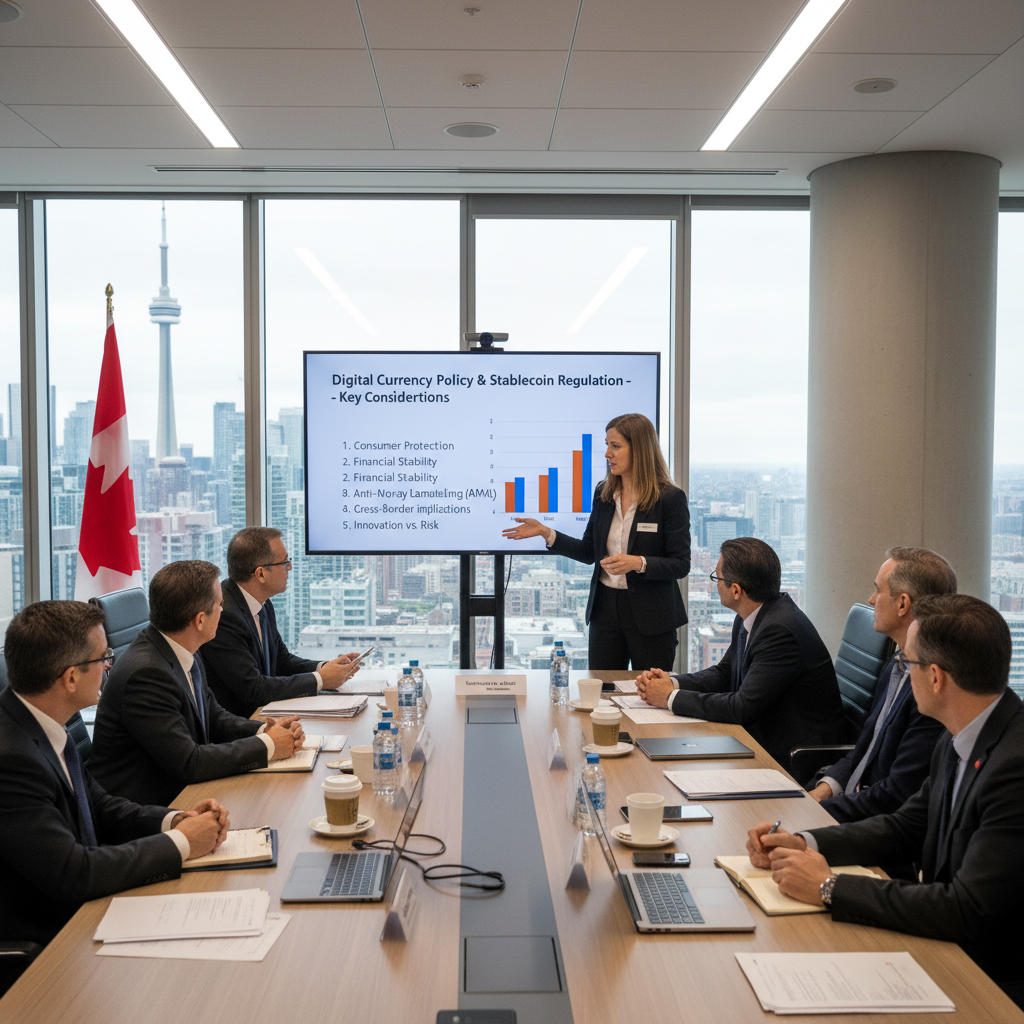
The impending arrival of USD1, a U.S. Treasury-backed stablecoin with political connections, has triggered urgent policy debates in Ottawa, forcing Canadian regulators to confront fundamental questions about monetary sovereignty in the digital age. The development comes as the Bank of Canada quietly progresses with its own central bank digital currency (CBDC) prototype, setting the stage for a potential clash between government-issued and privately circulated digital dollars.
Canada’s financial system finds itself caught between competing pressures as USD1’s launch approaches. Major cryptocurrency platforms report surging Canadian interest in the stablecoin, while internal Finance Department documents obtained by The Financial Post reveal growing concern about “currency substitution risks” that could undermine the Canadian dollar’s dominance.
Carleton University economics professor Angela Redish warns that the stakes couldn’t be higher. “When citizens begin holding substantial wealth in U.S.-backed digital assets, we effectively surrender control over key monetary policy tools,” she explains. Her recent research suggests unregulated stablecoins could capture 5-7% of Canada’s money supply within three years—a scenario that would significantly constrain the Bank of Canada’s ability to manage inflation and respond to economic shocks.
The Central Bank’s Dilemma
The Bank of Canada now faces critical decisions about how to respond to this emerging challenge. According to sources familiar with the discussions, the central bank is evaluating three primary options: accelerating its digital loonie initiative currently slated for research until 2026, implementing strict new stablecoin regulations through the upcoming Financial Institutions Act review, or developing technical standards that would permit controlled circulation of USD1 within Canada’s financial system.
Deputy Governor Sharon Kozicki recently emphasized to Parliament’s Finance Committee that “all options remain on the table,” while stressing that preserving financial stability remains the institution’s top priority. This delicate balancing act comes as the central bank advances work on its CBDC prototype, known internally as “Project Jasper.”
Deep Divisions Across Industries
The USD1 debate has exposed significant rifts within Canada’s financial sector. Traditional banks, led by RBC and CIBC, have launched aggressive lobbying efforts for strict limits on stablecoin usage, citing concerns about potential deposit outflows to digital alternatives.
Meanwhile, fintech firms including Wealthsimple and Bitbuy argue that Canada risks falling behind in payments innovation if it doesn’t create a regulated framework for stablecoin access. The export sector appears divided—while manufacturers see potential cost savings in USD1’s cross-border settlement capabilities, others worry about increased exchange rate volatility if dollarization accelerates.
“Canadian businesses process $2.6 billion in cross-border transactions every single day,” notes Rhonda Barnet, Vice President at the Canadian Chamber of Commerce. “Even marginal efficiency gains from stablecoin adoption could create overwhelming pressure for businesses to switch.”
A Race Against Time
With USD1 expected to launch before 2025, Canadian regulators face a series of critical deadlines that will shape the country’s digital currency landscape. The Financial Transactions and Reports Analysis Centre of Canada (FINTRAC) must finalize new cryptocurrency reporting rules by June 2024, while the Office of the Superintendent of Financial Institutions (OSFI) is expected to issue updated stablecoin guidance this September.
Perhaps most crucially, the Bank of Canada faces a January 2025 decision point on whether to proceed with a CBDC pilot—a timeline that now appears increasingly compressed due to the USD1 factor.
This regulatory crunch has created extraordinary challenges for policymakers attempting to simultaneously preserve monetary sovereignty, encourage fintech innovation, prevent political interference in financial systems, and maintain seamless cross-border commerce. As one senior Finance official acknowledged on condition of anonymity, “We’re effectively writing the rulebook as the game is already being played.”
Possible Paths Forward
International precedents offer Canada several potential models for addressing the stablecoin challenge. The Singapore approach of strict licensing for foreign stablecoins with usage caps and reserve requirements presents one option. Alternatively, Canada could follow the UK’s path of treating stablecoins equivalently to bank deposits with full consumer protections.
A third possibility involves developing a uniquely Canadian solution—perhaps a hybrid system that links the proposed digital loonie to regulated private alternatives.
“The USD1 situation may finally force Canada to define its vision for digital currency,” suggests Jeremy Kronick, fintech lead at the C.D. Howe Institute. “Continuing to hedge our bets risks becoming the worst possible strategy at this critical juncture.”
With Canadian households already holding over $16 billion in cryptocurrency assets according to Ontario Securities Commission data, the coming months will determine whether Canada can proactively shape its financial future or find itself perpetually reacting to innovations originating beyond its borders. As the world watches this unfolding experiment in monetary sovereignty, one reality has become inescapable: the era of passive currency policy has reached its end.